The
affordable
simpler
path
to healthcare
affordable
simpler
Health Savings Accounts (HSAs) empower you to save more and spend smarter, and invest in your future. Open an HSA and make your first contribution — we’ll match your first $25.1
HealthEquity does not verify whether you meet the eligibility criteria per IRS publication 969 to open and contribute to an HSA. You must verify your own eligibility status before you proceed.
Now includes
ACA Bronze plan
members
members
Why choose HealthEquity?
 24/7 support
Expert support that’s ready for you whenever you need it—just a call or click away, around the clock.
Help Center Everyday savings
Use your HSA with confidence—from doctor’s visit to medical expenses—with ways to instantly check what qualifies.
See Qualifying Expenses Easy mobile access
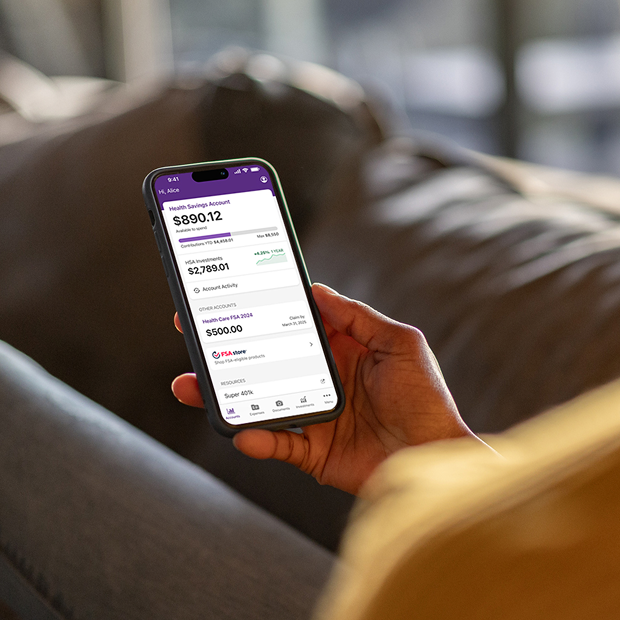
Pay for medical expenses with your HSA card5 or mobile app. Manage on the go—check balances and contributions from your phone.
Download Mobile AppYour HSA. Your way.
Pay for healthcare
Use your HSA for a wide range of eligible expenses—from doctor visits and allergy medications to sunscreen and select prescription treatments like GLP‑1s.
Funds never expire
You can roll over contributions from year to year, with no deadline to use them.
Use pre-tax dollars3
Helps make health expenses easier to manage, so you can save for other things that matter.
Save for the future
An HSA offers ways to watch your money grow, to build a nest egg or use toward tomorrow’s health needs.
Who’s eligible for an HSA?
You can open and contribute to an HSA if you’re enrolled in an HSA-eligible health plan, such as a Bronze or catastrophic plan or another high-deductible health plan. You also can’t have other disqualifying health coverage, be enrolled in Medicare, or be claimed as a dependent on someone else’s tax return.
1
Sign up online
We’ll collect some information to start and verify your account.
2
Connect your bank
We’ll link your account through a secure financial platform.
3
Contribution from you.
Match from us
Match from us
Make a one-time transfer of $25 to activate your account and get a $25 match from us.
More affordable healthcare for Bronze plan members — that’s the better path!
Simple health savings that work alongside your Bronze plan benefits. Plus $25 on us when you open and fund your HSA.
Open an HSA1 The $25 match is a limited-time offer, subject to change or termination at any time.
If you currently have active HDHP coverage and otherwise meet eligibility requirements as defined by IRS Publication 969: To receive the match, you must contribute $25 or more within 180 days after the later of: (i) the date your HealthEquity HSA is opened; (ii) the effective date of your HDHP coverage, if coverage has not yet started when your HSA is opened; or (iii) the campaign start date for existing HSA contributors. In addition, your account must remain in good standing and maintain a minimum balance of $25 for at least 90 days following your qualifying contribution or account opening date, as applicable. HSA contributions are subject to eligibility and other restrictions as defined in IRS Publication 969.
If your HDHP coverage hasn’t started yet: You may qualify for HSA contributions on or after your plan’s effective date. To receive the match, you must contribute $25 or more within 180 days after the later of: (i) the date your HealthEquity HSA is opened; (ii) the effective date of your HDHP coverage, if coverage has not yet started when your HSA is opened; or (iii) the campaign start date for existing HSA contributors. Your account must also remain in good standing with a minimum balance of $25 for 90 days before the matching contribution is awarded.
All contributions, including the one-time $25 match, count toward your annual HSA contribution limit as established by the Internal Revenue Service (IRS) for the applicable tax year. You are solely responsible for ensuring that your contributions do not exceed IRS limits, and HealthEquity is not liable for contributions that exceed those limits. Participation in this promotion is optional and does not affect other rights or benefits under your HSA. HealthEquity reserves the right to cancel, suspend or modify this promotion at any time and in our sole discretion.
2 HSAs are never taxed at a federal income tax level when used appropriately for qualified medical expenses. Also, most states recognize HSA funds as tax-deductible with very few exceptions. Please consult a tax advisor regarding your state’s specific rules.
3 Catch Up Contributions: HSA eligibility and contribution limits are determined by the IRS. To contribute – including the $1,000 catch-up contribution available beginning at age 55 – an individual must meet the eligibility requirements under IRC §223(c)(1) (e.g., be covered by a qualified high-deductible health plan and have no disqualifying coverage) and may not be claimed as a tax dependent under IRC §152. Each eligible spouse must have their own HSA to make catch-up contributions, and HSA contributions must stop once an individual enrolls in Medicare. If both spouses are HSA-eligible under family coverage, the annual contribution limit applies to both of you together and must be shared between your HSAs; please consult your tax advisor for guidance on allocation.
4 Young Adult Eligibility: HSA eligibility is determined by the IRS. To be eligible to open and contribute to an HSA, an individual must meet the requirements in Internal Revenue Code § 223(c)(1), which includes being covered under a qualified high-deductible health plan and having no disqualifying coverage. In addition, an individual who can be claimed as a tax dependent under Internal Revenue Code § 152 is not eligible to open an HSA (IRC § 223(b)(7)). Once a young adult is no longer claimed as a tax dependent and continues to meet the other HSA eligibility requirements, they may open and contribute to their own HSA.
HealthEquity does not provide legal, tax, or financial advice. Please consult a qualified tax professional to understand any potential tax consequences related to receiving this matching contribution.

Language Assistance / Non-Discrimination Notice
Asistencia de Idiomas / Aviso de no Discriminación
語言協助 / 不歧視通知
Asistencia de Idiomas / Aviso de no Discriminación
語言協助 / 不歧視通知
HealthEquity does not provide legal, tax or financial advice.